

The Hay Market Is Tightening, and Freight Is Making It Worse
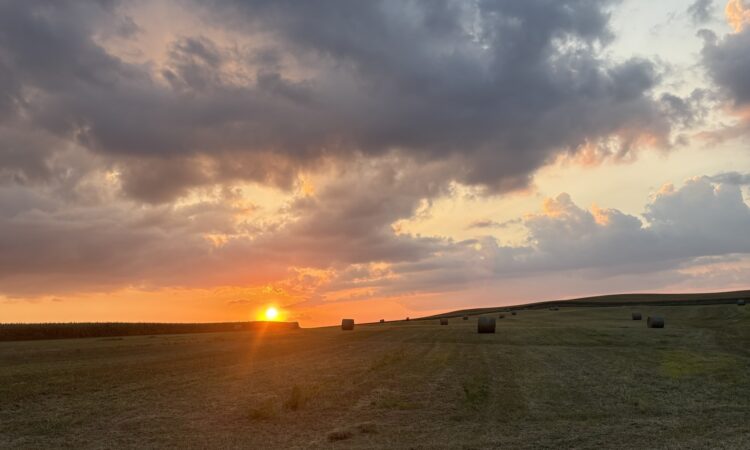
Corn has a futures contract. So do soybeans, wheat, cattle, even orange juice. Hay, a crop farmers grow on nearly 50 million acres, doesn’t. There’s no ticker and no exchange. Prices come from sale barns, phone calls, and a few dozen USDA market reports a week, each in its own format.
That makes hay easy to ignore until it isn’t. This fall, it’s hard to ignore.
A smaller shortage on paper
USDA’s Oct. 9 Crop Production report put 2026 U.S. hay production at 120.5 million tons, down 2.0% from last year’s 123 million. That is a smaller gap than the 113.3 million tons USDA forecast in August. Alfalfa is now forecast at 50.6 million tons, slightly above last year. Other hay, mostly grass, is forecast at 70.0 million tons, down about 4%.
Carryover is a little lighter, too. USDA put May 1 hay stocks at 23.3 million tons, down 3% from a year earlier. Add that to the new production number and the season’s total hay supply is down only about 2%.
But a national total hides where the hay actually is. In Virginia, Gov. Abigail Spanberger declared a state of emergency in September over an estimated 500,000-ton hay shortfall, close to a fifth of the state’s 2025 crop. Yields were down 35% statewide and up to 70% in some areas. In Wyoming, a state that usually sells hay, a USDA market reporter wrote in September that it was the “first time since I have been reporting this hay market in Wyoming where a rancher or livestock owner is bidding more for hay than the dairies are willing to pay.”
The real problem is moving it
Hay is bulky and cheap per pound, so freight is a big share of what a buyer ends up paying. That matters when the hay is in one place and the shortage is in another.
In mid-October, USDA’s Wyoming report said some out-of-state buyers had turned back loads they’d already agreed to because diesel and freight got too expensive. Some of them had been buying western Wyoming hay for 10 years or more. Energy prices overall were up 20.4% in September from a year earlier, according to the Bureau of Labor Statistics.
And hay prices aren’t easy to see. USDA’s latest Texas report listed only asking prices, with no confirmed sales, for the second report in a row.
Prices are still elevated
The federal government’s Producer Price Index for hay and hayseeds rose from 333.7 in April to 432.7 in September, a 30% jump in five months.
Dairies feel that directly. USDA’s dairy alfalfa price, which feeds the federal Dairy Margin Coverage program, averaged $243 a ton in August, up from $222 a year earlier. With milk prices soft, August was the third month this year that DMC paid out.
HayWire’s national index, built from USDA-reported sales, was $169 a ton for the week of Oct. 19, drawn from confirmed sales in 28 markets. The spread inside it is the real story. In hay, grade, location and freight set your price far more than any national average does.
What it looks like in Minnesota
Minnesota’s hay looks cheap on paper. Our four-week state average is about $126 a ton, among the lowest we track. But that average comes from a single USDA-reported market, and it mostly reflects what happens to be selling.
At the Pipestone Hay and Straw Auction on Oct. 27, 137 tons of hay sold, about the same as a year earlier. Good alfalfa in large rounds brought $175 a ton, up from $155 a week earlier, though only about 9 tons of it sold. Good grass averaged about $162 and good alfalfa-grass mix $165. Fair grass, half the day’s hay at 69 tons, averaged about $115. Prices at a single auction move with what’s offered that day, but good grass sold for more than $45 a ton above fair grass.
The weather helped, then stalled. Late-September rain pulled northwestern Minnesota out of drought, but the latest U.S. Drought Monitor, released Oct. 22, shows little change since early October. Still, 36% of the state is in moderate drought, 25% in severe drought, and 3% in extreme drought. In Wisconsin, 22% of the state remains in extreme or exceptional drought.
For Minnesota producers with good hay to sell, that’s a market. A short crop in one region pulls hay from the regions that have it, and the Upper Midwest is closer to the shortage areas than California or the Pacific Northwest.
Why hay shows up in your grocery bill
Hay is a cost input for beef and dairy. When it gets scarce, ranchers sell cows rather than buy expensive feed. The U.S. cattle herd is already at its smallest since the 1950s, and USDA counted 28.5 million beef cows on July 1, down 1% from a year earlier.
Retail beef and veal prices were up 5.9% in August from a year earlier. In September the increase eased to 3.5%, after a 1.3% drop in the month. USDA now projects beef and veal prices to rise 8.7% for 2026 as a whole.
What to watch
- Freight: with energy costs up, hay moving long distances will carry a bigger delivered price.
- USDA’s next hay estimate: the October revision showed how much the national number can move.
- Rain on the High Plains and Upper Midwest: continued improvement could take pressure off prices into spring.
- The herd: if ranchers keep selling cows, beef supplies stay tight no matter what hay does.
Hay doesn’t trade on a screen. But the signals are there for anyone willing to read the reports, and this fall they say the same thing: a smaller shortage than feared, but a hay market where freight and location decide who pays what.
Aiden Johnson is the co-founder and CEO of HayWire, a market intelligence platform that brings price transparency to the U.S. agricultural hay market.