

Medtronic’s Diabetes Split-Off Drew a Crowd. Now MiniMed Has to Deliver.
When Fridley-based Medtronic announced earlier this year it would split-off MiniMed, its diabetes business, investors expressed interest in exchanging their shares.
On Oct. 15, Medtronic reported it had a 5.4x oversubscription for its exchange offer for MiniMed. While all shareholders with 100 shares or less received a full exchange, a Medtronic spokesperson tells TCB that allocations were done “pro rata for holders who tendered more than 100 shares.” Medtronic said it returned the remaining shares that weren’t able to be exchanged back to its shareholders.
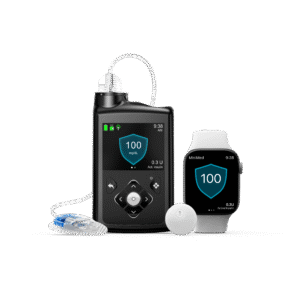
Following the split, MiniMed is officially an independent business and has moved its operational headquarters to California. Medtronic retained 0% equity ownership in the new entity. The move is part of a larger push to sharpen the company’s focus on higher-growth opportunities across cardiovascular care, neuroscience, surgical technologies, and robotics, a company spokesperson told Twin Cities Business in a July story about its acquisition activity in 2026.
So, what does this all mean for Medtronic moving forward?
Medtronic’s Bet
For Medtronic, the split-off is primarily about concentrating resources on its other businesses.
But by separating MiniMed, Kevin Orth, a retired business development director for 3M and a guest lecturer at the University of St. Thomas Opus College of Business, says Medtronic “can also control operating expenses on its diabetes business.” And because “Medtronic has historically been a significant dividend payer, retiring the Medtronic shares accepted in the exchange reduces the number of outstanding shares on which it pays dividends,” he adds.
That does not mean Medtronic has eliminated every financial consequence. The company exchanged shares rather than receiving a cash payment for its remaining stake, and it gave up any future ownership-related upside from MiniMed. The potential benefit is a more focused business with fewer competing demands for capital.
The broader question is, will investors reward Medtronic for becoming a more streamlined company?
Matt Arens, founder and CEO of Edina-based First Light Asset Management, says, “sometimes it spins out for negative reasons, like if it’s not an attractive business segment or its growth is dragging. So, spinning it out is a way to capture value and to try to create a vehicle of a self-standing business that can garner a more significant multiple rather than be buried in the portfolio of the parent company.”
For Medtronic, the split-off means shareholders can now evaluate its remaining portfolio with a clearer view.
The deal is considered a split-off, rather than a spin-off, Orth explains, because Medtronic gave its investors an exchange offer to voluntarily choose whether to surrender—or exchange—all or part of their parent company stock in return for shares in MiniMed. In a spin-off—like what 3M did with Solventum—existing employees receive shares of the new subsidiary based on a fixed ratio without having to give up anything. So, they end up with stock in both entities, Orth adds.
Why are large med-device companies breaking themselves apart?
Medtronic is not the only major medical device company to break off one of its businesses this decade.
3M spun off its healthcare business as Solventum in 2024, while Johnson & Johnson spun off its consumer health business, Kenvue, in 2023. Those transactions presented similar questions: Does a collection of businesses create more value together, or would investors value them more highly as independent companies?
“There has for a long time [been] a trend to consolidate businesses [in this industry] together,” Arens says. “That was the flavor of the day for a significant period of time.”
Now, companies are taking another look at their portfolios and asking whether individual businesses could perform better independently.
RELATED: Why Is Medicare Advantage Exiting Dozens of Minnesota Counties in 2027?
One reason is that different investors have different priorities. Some want established companies with dependable cash flows and dividends. Others are looking for businesses with faster growth and greater upside potential, even if they carry more risk.
Orth also points to the growth of capital markets and the availability of investors willing to fund newly independent companies. “Right now, there is a lot more investor money available in capital markets that did not exist 10-20 years ago,” he says. “Part of this is investment banks wanting to create new, investible entities.”
Arens says anything that leads to a healthy Medtronic is a good thing for the Twin Cities market. “The fact they are making moves is a healthy thing because they are manually managing their portfolio,” he says.
The ball is now in MiniMed’s court. It has to prove to its new shareholders that it can sustainably grow, and that independence was worth the bet on future growth.